A crypto long/short ratio compares a defined group’s long exposure with its short exposure, often by counting accounts rather than position size. A ratio above one means more of the measured long quantity than short quantity; it does not mean more money entered longs or that price must rise. Identify the venue, contract, population and counting method before interpreting the number.
That definition check comes before deciding whether a reading looks bullish, crowded or suitable for a contrarian trade. Two charts labeled “long/short ratio” can answer different questions. This guide uses hypothetical accounts to show why, then provides a worksheet for recording a defensible observation.
Start with the thing being divided
For an account ratio, divide the number of accounts classified as long by the number classified as short. Each included account contributes to the count rather than contributing its position’s monetary value.
Bybit’s long/short account-ratio documentation defines long and short shares using the numbers of holders, then divides the long share by the short share. Its endpoint distinguishes linear USDT contracts from inverse contracts and takes a symbol and recording period. Those parameters belong beside any downloaded value.
Binance USDⓈ-M Futures publishes separate all-trader account, top-trader account and top-trader position ratios. Its top-trader group is the 20% of users with the highest margin balance; the account measure counts each account once, while the position measure describes that group’s long and short positions. “Top” here describes a selection rule, not a verified record of trading skill. See the definitions in Binance’s futures market-data documentation.
| Label to verify | What the reading can describe | What it cannot establish alone |
|---|---|---|
| All-trader account ratio | Relative counts in the venue’s included account population | Position size or total market direction |
| Top-trader account ratio | Relative account counts within a selected group | That the group is profitable or unhedged |
| Top-trader position ratio | Relative long and short positions within that group | The exposure of every other participant |
A provider may use another definition. Save its explanation rather than translating every field into the same label. “Global accounts” can still mean accounts on one exchange, not all crypto traders worldwide.
Six small longs can face one larger short
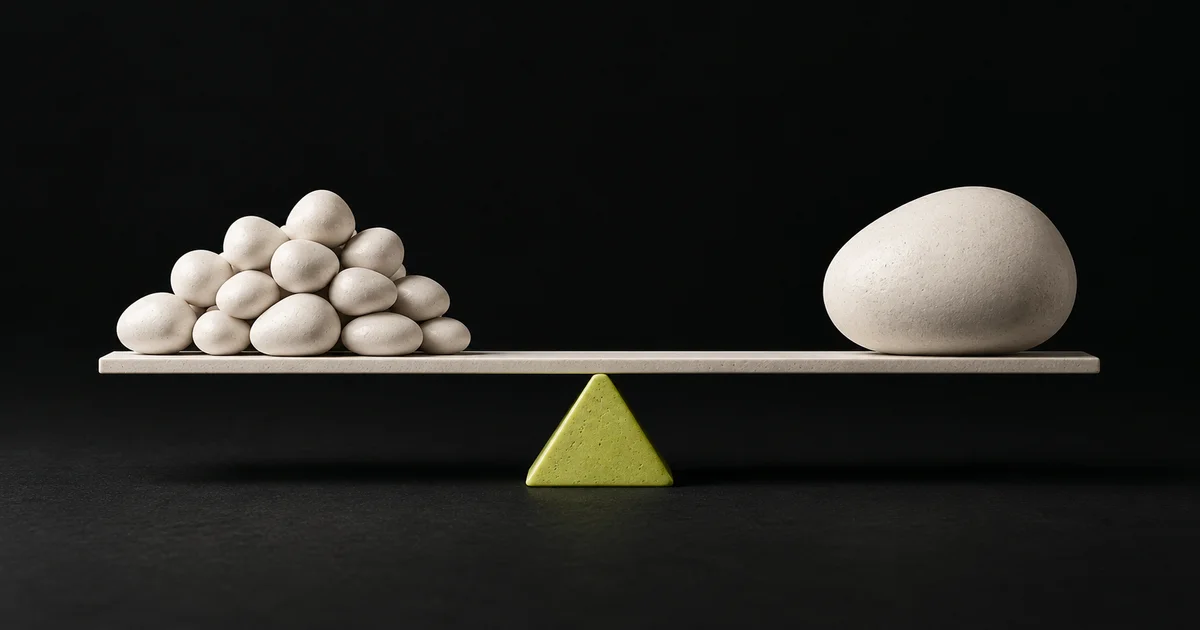
Imagine a complete fictional market in one identical futures contract. Six accounts each hold one long contract. One other account holds six short contracts. There are no additional positions or hedges in this construction.
| Hypothetical group | Accounts | Contracts per account | Total contracts |
|---|---|---|---|
| Long holders | 6 | 1 | 6 long |
| Short holder | 1 | 6 | 6 short |
The account ratio is 6 ÷ 1 = 6.00. Long accounts represent 6 ÷ 7 ≈ 85.71% of holders, while short accounts represent approximately 14.29%. Yet total long and short contract quantities both equal six.
The example is consistent with matched futures obligations: each outstanding contract has a long and a short side. CME’s explanation of volume and open interest makes the buyer-and-seller relationship explicit. Its venue reporting is separate from crypto exchange account statistics, but the accounting distinction explains why a headcount imbalance does not require unmatched contracts.
The open-interest versus volume ledger follows a different denominator: outstanding contracts rather than holder counts. It shows how heavy trading can transfer existing exposure without creating an equal increase in open interest.
Now let those six long contracts transfer from six holders to two holders, each with three. Keep the six-contract short unchanged. The account ratio falls to 2 ÷ 1 = 2.00, although long quantity and short quantity remain six. A falling account ratio alone cannot tell you that aggregate long exposure shrank.
An account is also not necessarily one person, one organization or one independent opinion. Public account statistics do not reveal common control or exposures outside the measured instrument. Avoid turning an account census into a census of conviction.
Convert ratios and percentages carefully
If long and short shares exhaust the included population, a ratio R converts to a long share of R ÷ (1 + R). The corresponding short share is 1 ÷ (1 + R).
For a hypothetical ratio of 1.5, the long share is 1.5 ÷ 2.5 = 60%; the short share is 40%. A ratio of 2 means approximately 66.67% long, not 200% of participants long. Equal shares produce a ratio of one.
Keep the population assumption explicit. If a provider includes neutral accounts, uses an unusual hedge-account classification or reports a different quantity, this conversion may not apply. Resolve that definition first.
Use unrounded source shares when checking a displayed ratio. Rounded 66.7% and 33.3% produce approximately 2.003 rather than exactly two. Small differences can be rounding; a large inconsistency requires investigation. A zero short denominator makes an ordinary finite ratio undefined, while a missing field says nothing about whether the market is balanced. Neither should silently become one.
Why a high ratio is not an automatic reversal signal
A high account ratio can motivate a crowding hypothesis: perhaps many included accounts share a direction. It does not reveal their entry prices, leverage, liquidation levels, stop orders or ability to add collateral. Without those details, it cannot locate a liquidation cascade or assign its probability.
Nor does a short futures position prove a bearish portfolio. A hypothetical holder could own spot BTC and short a related futures position as a hedge. The ratio shows the classified derivative exposure; it does not explain the holder’s complete investment view.
Following the majority and fading the majority are both strategy hypotheses. Either needs an entry definition, holding horizon, exit rules and testing. There is no universal ratio of two, three or another number that makes one action valid across contracts and venues. A statistic can remain unusual while price continues moving against a contrarian position.
Keep funding separate too. A headcount ratio does not itself specify the next funding rate or the cash payment on your position. The perpetual basis versus funding guide distinguishes the current price gap from a settlement rate, while the perpetual funding-cost ledger handles payments using the relevant rate, contract units and settlement rules.
Record a ratio observation before using it
Use this worksheet for a research note or an AI analysis review. The example values are invented and do not describe a current market.
| Field | Hypothetical record | Reason to retain it |
|---|---|---|
| Source and market | Venue A, BTCUSDT linear perpetual | Prevents spot, inverse and cross-venue substitutions |
| Measure | All-trader net account ratio | Fixes the counting method |
| Observation | 60% long, 40% short, ratio 1.50 | Makes the arithmetic inspectable |
| Recording period | One hour | Separates it from another sampling interval |
| Time | Period ended 12:00 UTC; received 12:02 UTC | Distinguishes observation from availability |
| Comparison | Same series’ prior observations | Avoids comparing different populations |
| Interpretation | More included accounts classified long | States only what the measure supports |
| Unresolved | Unknown leverage and external hedges | Prevents invented explanations |
Bybit explicitly warns that delivery of this data may be delayed during extreme volatility. Treat freshness as part of the observation, especially when another data feed is already newer. The market-data freshness guide explains the relevant clocks.
If a live ratio arrives two minutes after its period ends, a backtest must not assume it was available at the ending timestamp. Record actual availability where possible; otherwise state the assumed delay. The look-ahead-bias audit provides a way to test whether later information changed earlier decisions.
Do not average exchange ratios and call the result a combined account ratio. For example, one venue with 60 long and 40 short accounts has a ratio of 1.5; another with one long and nine short has approximately 0.1111. Their simple mean is approximately 0.8056, but their combined counts give 61 ÷ 49 ≈ 1.2449. Even that combined count would count accounts rather than distinct people. Without compatible definitions and underlying counts, report the series separately.
Save the narrow conclusion
A useful conclusion is: “In this venue’s recorded population, the long account share increased under an unchanged definition.” A claim that informed traders bought, that a reversal is imminent or that a position is safe requires different evidence.
Store the raw observation, source definition and alternative explanation in the trading decision journal. This article does not establish a native KLINEO long/short-ratio feed or trading rule. It explains how to review such data wherever it is obtained.
All account sets and arithmetic examples here are hypothetical teaching constructions. The article was prepared with AI assistance under the editorial policy. Correctly identifying a crowd still does not establish a profitable trade or prevent trading losses.