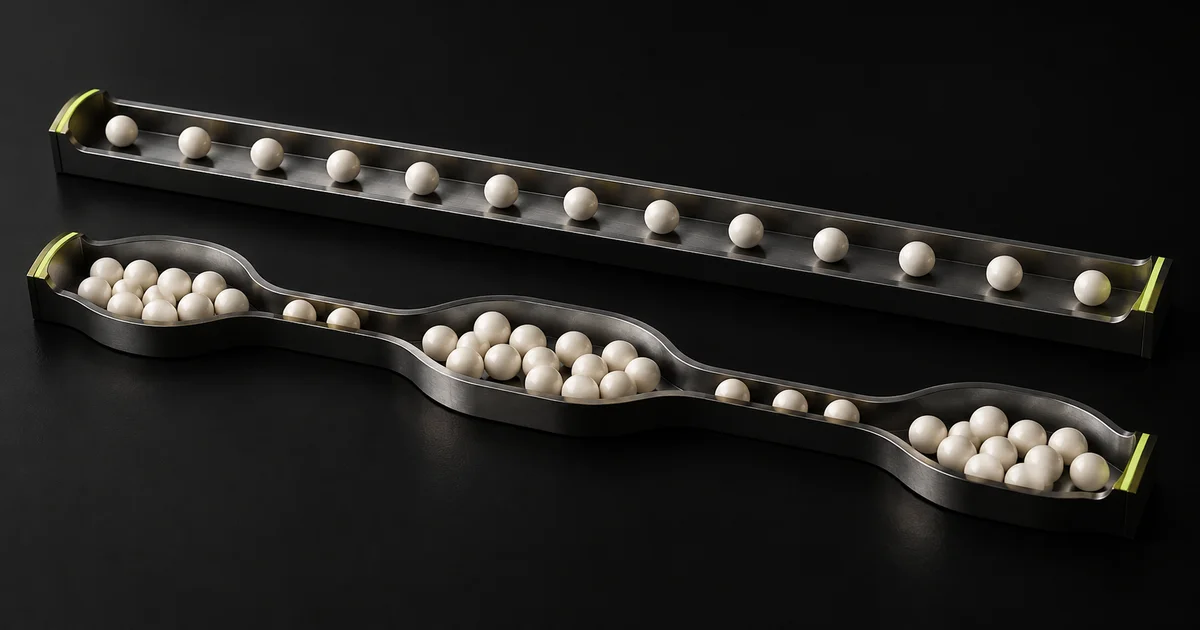
TWAP execution spreads a parent order roughly evenly across a chosen time window. VWAP execution typically varies child-order sizes to follow an expected volume profile, aiming to track a volume-weighted price benchmark. In crypto, choose between them by specifying the venue, instrument, deadline and participation limits; neither schedule guarantees the benchmark price or a complete fill.
The practical question is how much of the intended order should reach the market during each interval. That is separate from interpreting a price line on a chart. The VWAP session and anchor guide covers that analytical use; here the focus is an execution instruction with a finite quantity and unfinished work to manage.
Separate the benchmark, schedule and child order
A benchmark is a reference price measured over a declared window. A schedule allocates the parent quantity across that window. A child order is the actual instruction submitted to trade one allocation. Choosing a schedule does not determine whether every child is a market order, a resting limit order or a combination.
For equal-duration intervals, a simple TWAP schedule assigns the same quantity to each interval. A volume-profile schedule assigns more quantity to intervals expected to carry more trading volume. Coinbase Prime's VWAP order documentation provides a concrete example: its implementation weights executions using historical volume and explicitly does not adjust those quantities for current market conditions.
That qualifier matters. A VWAP label does not prove that an algorithm observes current volume, predicts it accurately or follows the exact pair you are trading. Ask what profile it uses and whether it updates during execution. Keep an expected-volume schedule distinct from a percentage-of-volume instruction that reacts to observed trading activity.
Scheduling is also different from hiding displayed size. An iceberg order's visible slice controls what appears on the book; a TWAP or VWAP schedule controls when quantities are allocated. Read the actual venue rules before assuming one implies the other.
A four-interval allocation worksheet
Consider a hypothetical parent order to buy 20 base units during a one-hour window on one named spot market. Divide the hour into four equal 15-minute intervals. Assume all quantities are valid for the venue and ignore fees initially. These are teaching inputs, not observed market data or suggested order sizes.
The expected external market volume is 1,000 base units, distributed as 10%, 20%, 50% and 20%. “External” means volume excluding this example's own purchases, so the participation denominator remains explicit.
| Interval | Expected external volume | Expected volume share | Simple TWAP allocation | Volume-profile allocation |
|---|---|---|---|---|
| First 15 minutes | 100 units | 10% | 5 units | 2 units |
| Second 15 minutes | 200 units | 20% | 5 units | 4 units |
| Third 15 minutes | 500 units | 50% | 5 units | 10 units |
| Final 15 minutes | 200 units | 20% | 5 units | 4 units |
| Total | 1,000 units | 100% | 20 units | 20 units |
The calculations are straightforward: TWAP quantity per interval is 20 ÷ 4 = 5. Each volume-profile allocation is 20 multiplied by that interval's expected volume share.
Now divide each allocation by the corresponding expected external volume. TWAP participation is 5%, 2.5%, 1% and 2.5%. The volume-profile schedule is 2% in every interval. Under these assumptions, it concentrates quantity where more activity is expected rather than requiring the same five units in the quietest interval.
This is an allocation comparison, not proof of lower market impact. Executed volume is not the same as resting liquidity available to your order. Spreads, cancellations, competing orders and price movement still matter; the order-book depth worksheet shows why a total volume figure cannot price an immediate child order.
The volume forecast can fail at the busiest bucket
Change just one assumption: actual external volume in the third interval is 100 units instead of 500. The planned ten-unit child is now 10% of that interval's external activity. Its expected participation was only 2%.
Suppose the operator's hypothetical policy caps purchases at 3% of external volume measured over each completed interval. Retrospectively, the third interval allows at most three units. A live controller would need a defined observation cadence and rules for responding to newly observed volume; it cannot use the completed interval's total in advance.
If the other slices fill as planned and there is no catch-up, the parent fills 2 + 4 + 3 + 4 = 13 units. Seven units remain. The operator cannot preserve the original volume forecast, a hard participation cap and guaranteed completion merely by calling the instruction VWAP.
Catch-up needs its own authority: may later slices grow, may the deadline extend, or must the remainder stop? Hyperliquid's native TWAP documentation illustrates this tradeoff in a specific implementation. It describes constrained catch-up after missed child fills and warns that the full parent size may remain unfinished. That behavior should not be generalized to every exchange.
Before choosing more intervals, check execution slice minimums. A valid parent does not guarantee that small child allocations are tradable. Rounding or rejected children can create a backlog even when the volume forecast is correct.
Measure the right average after execution
For actual fills, average execution price equals total quote amount paid divided by total base quantity filled, excluding fees unless the report explicitly incorporates them. For a market VWAP benchmark, use market trades and their volumes over the same declared window and venue set. Those are different datasets.
Continue the hypothetical four-interval example with representative market prices of 100, 102, 98 and 101 quote units per base unit. For this simplified benchmark calculation, assume every external trade within an interval occurs at its representative price.
The external-market VWAP is:
(100 × 100 + 102 × 200 + 98 × 500 + 101 × 200) ÷ 1,000 = 99.60.
The equal-time average of those four interval prices is (100 + 102 + 98 + 101) ÷ 4 = 100.25.
If every planned child could fill exactly at those representative prices, the volume-profile schedule would average 99.60 and TWAP would average 100.25. This result follows from the constructed weights. It does not establish an attainable price: the example excludes spread, price impact, timing within intervals, fees and incomplete fills. Another price path can reverse which schedule has the lower average purchase price.
Record the original requested quantity alongside average price. An attractive price on 13 filled units is not equivalent to completing a 20-unit parent. The partial-fill management guide explains the remaining-quantity ledger, including orders still working or unresolved.
Write the completion policy before starting
Use this compact worksheet when comparing an exchange's algorithm descriptions:
| Decision | What the specification must say |
|---|---|
| Parent intention | Buy or sell; base quantity or quote budget; exact instrument |
| Window | Start, deadline and timezone; whether extension is permitted |
| Allocation | Equal-time quantities or a named expected volume profile |
| Volume scope | Venue set, instrument, units and treatment of the order's own fills |
| Child authority | Order type, price boundary, size limits and valid increments |
| Missed slice | Stop, defer or catch up; maximum permitted later quantity |
| End state | Filled quantity, working children, canceled quantity and unresolved submissions |
| Evaluation | Common benchmark window, fees and completion percentage |
A steady clock-based schedule may be easier to inspect when there is no credible volume profile. A volume-profile schedule may better match the intended benchmark when its assumptions are defensible. Both leave price risk while work remains; a rapidly changing exit requirement may be incompatible with a long schedule.
This article was prepared with AI assistance under the editorial policy. The worksheets explain execution design and accounting. The venue examples do not establish that KLINEO exposes TWAP, VWAP or participation-cap controls.