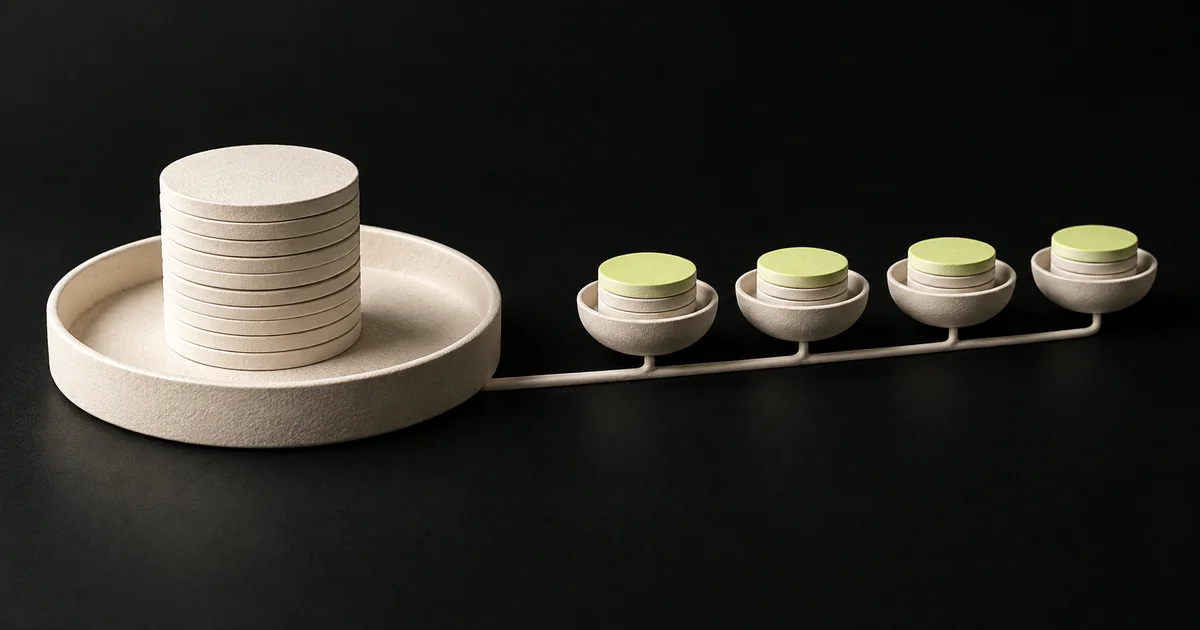
A DCA bot's base order sets the exposure opened immediately, while safety orders plan further purchases for specified conditions. Compare their sizes within the same full-deal budget: a smaller base leaves more buying capacity for later, but less exposure if price rises before any addition. No base-to-safety ratio guarantees a recovery or a smaller loss.
The ratio hides how much you deploy at the start
In a long averaging strategy, the base order is the initial purchase. Safety orders, also called averaging orders, add to that position after their conditions are met. The word “safety” describes the order's role; it does not mean the purchase protects capital.
The 3Commas TradingView script parameter guide separates the base-order amount, first safety-order amount and multiplier for subsequent safety orders. Those are definitions for that documented script, not evidence that every trading platform implements identical rules.
A 1:1 base-to-safety ratio does not mean half the budget enters immediately. With four equal safety orders, the base is one of five equal purchases: only 20% of the full purchase budget. The count matters as much as the ratio.
For a fixed quote-currency budget T, base amount B, four equal additions of S, and no size multiplier:
T = B + 4 × S
More generally, with N equal additions and r = S / B:
Initial share = B / T = 1 / (1 + N × r)
Keep the ratio's direction explicit. “Two times the base” means S/B = 2; “base is twice the safety order” means S/B = 0.5. Writing the amounts prevents that reversal.
Compare three splits of the same $1,000 budget
The following is a hypothetical unleveraged spot exercise. An invented asset's base purchase fills at $100, with four later purchases at $95, $90, $85 and $80. All safety orders within each plan have equal quote value. There are no fees, spread, slippage, rounding, partial fills or sales during the comparison. Quote currency is assumed to retain its value.
| Allocation | Base purchase | Each of four additions | Initial budget share | Safety/base ratio |
|---|---|---|---|---|
| Larger initial purchase | $600 | $100 | 60% | 0.167 |
| Equal purchase amounts | $200 | $200 | 20% | 1 |
| Larger later purchases | $100 | $225 | 10% | 2.25 |
Every row totals $1,000. Changing only the base while leaving every later order unchanged would change the total commitment and make this a different comparison.
At a smooth decline to $90, assume the base and first two additions have filled completely. The three plans have spent $800, $600 and $550 respectively. Their remaining planned purchase cash is $200, $400 and $450. A smaller base has delayed spending; it has not removed the commitment to buy later.
This is the split between early and conditional exposure. The capital-requirements worksheet handles whether the entire commitment fits beside the account's other obligations. Money reserved for this ladder cannot simultaneously fund a second one without creating a shortfall if both need it.
Calculate the average from units, not an average of prices
For quote-sized purchases, divide each purchase amount by its fill price to obtain units. Then divide total purchase cost by total acquired units:
Units = B/P0 + S/P1 + S/P2 + S/P3 + S/P4
Average entry = Total purchase cost / Units
For the equal-amount plan, the calculation is:
Units = 200/100 + 200/95 + 200/90 + 200/85 + 200/80 = 11.180427
Average entry = 1,000 / 11.180427 ≈ $89.44
The arithmetic average of the five prices is $90. It is not this position's average entry, because a $200 purchase acquires more units at $80 than at $100. Calculations below use unrounded quantities internally.
| Allocation after all five fills | Average entry | Rise from $80 to average | Gross marked P&L at $60 |
|---|---|---|---|
| Larger initial purchase | $94.43 | 18.03% | −$364.59 |
| Equal purchase amounts | $89.44 | 11.80% | −$329.17 |
| Larger later purchases | $88.28 | 10.35% | −$320.32 |
The last column is Acquired units × $60 − $1,000. It continues the scenario beyond the last planned buy. All three plans lose money there; all have exhausted their purchase budget. A lower average reduces the rebound needed to reach the gross purchase cost in this constructed path. It supplies no reason to expect that rebound.
Average entry is also not the final net break-even price. Fees and exit execution still matter. The take-profit and fees guide explains that separate calculation.
Test the path where the safety orders never happen
Now take a different hypothetical path: price rises directly from the $100 base fill to $110. None of the four lower orders fills, and there are still no sales or costs.
The larger-base plan owns six units and has a $60 unrealized gain. The equal-amount plan owns two units and has a $20 gain. The smaller-base plan owns one unit and has a $10 gain. Including the undeployed cash, their allocated-account values are $1,060, $1,020 and $1,010.
This is the cost of retaining later buying capacity: less participation in this immediate rally. It does not make one allocation preferable across unknown future paths. A comparison showing only fully filled ladders silently assumes the market first moves against every entry.
Real exit rules can end a deal before later purchases become eligible. Keep exits identical when comparing splits, and examine both completed and still-open deals. Counting only closed winners can hide capital tied up in an unresolved decline.
Keep restart timing fixed too. A cooldown between deals changes when the next base order may become eligible; that is a separate choice from how much the base order buys.
Keep sizing units and execution limits visible
“Base order” names the initial order. “Base currency” names the asset being traded. They are separate uses of the word base. The example uses quote-currency order values throughout.
The 3Commas strategy API reference distinguishes fixed coin amounts from fixed quote-value averaging. If each addition instead buys an equal number of coins, its cash cost falls as price falls, and this worksheet's equal-dollar assumptions no longer apply. A percentage-based setting also needs its balance denominator and recalculation rule written down before it becomes a cash amount.
A very small base introduces a practical failure case: it can fall below the chosen market's minimum order value. Binance's Spot filter documentation defines symbol-specific quantity increments and notional constraints. Rounding a proposed order down can change its value or make it invalid. Raising it to pass a minimum changes the initial share and may require reducing another purchase to preserve the budget.
Likewise, a touched price is not proof of a complete fill. After a partial fill, calculate actual cost and acquired units from executions. Do not assume an unfunded or rejected safety order lowered the average. Follow the partial-fill guide when the account diverges from the planned table.
An external purchase or sale also changes the ledger. The manual-intervention handoff guide explains how to reconcile that exception before automation resumes.
A reusable allocation review
Record these fields before choosing the split:
- Full purchase budget, excluded cash and a separate allowance for applicable costs.
- Base amount, each later amount, order count and sizing currency.
- Initial budget share and spending after each eligible addition.
- Average entry from acquired units for each assumed fill stage.
- Marked loss after the last addition, plus the rule that ends exposure.
- An immediate-rally path, a partial-fill path and a continuing-decline path.
Hold prices fixed for this exercise. Use the spacing guide to study different purchase levels and the volume-scale guide to study growing later amounts. Changing all three together makes it harder to identify why the result changed.
This worksheet covers spot purchases without borrowing. It does not model futures margin, funding or liquidation. Its useful output is a clear statement of when the budget becomes exposure, not an optimal ratio inferred from invented prices.
Editorial method: This AI-assisted article uses current primary documentation and independently checked hypothetical purchase calculations. It reports no observed trading performance or personalized allocation recommendation.